China can close the gate.
Fourteen minerals America can't build without are refined mostly in China, and Beijing now licenses exports of almost all of them. We're building everything from the mine to the strategic reserve, outside that gate.
How we got here
We were the arsenal. Now they are.
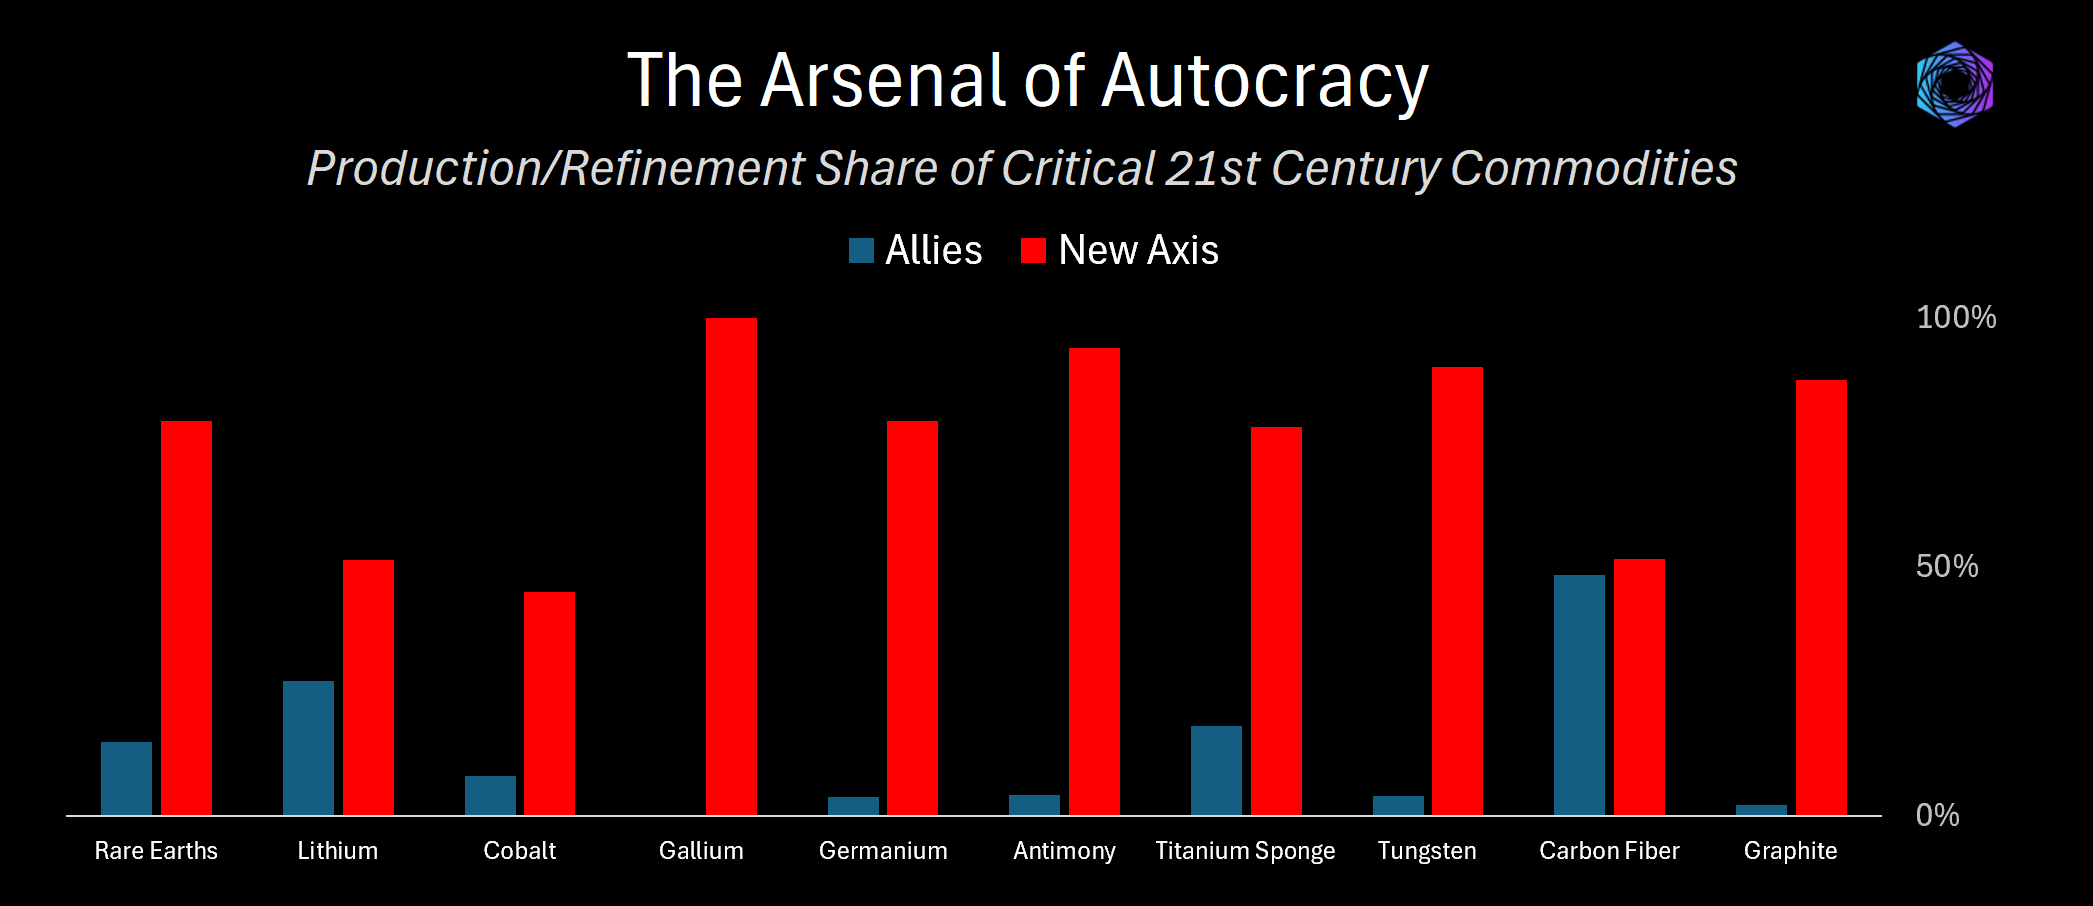
In 1945 the Allies made most of the world's steel, aluminum, copper and oil. Today the share has flipped. In the metals the 21st century runs on, China and its partners hold the refineries, and the gate along with them.
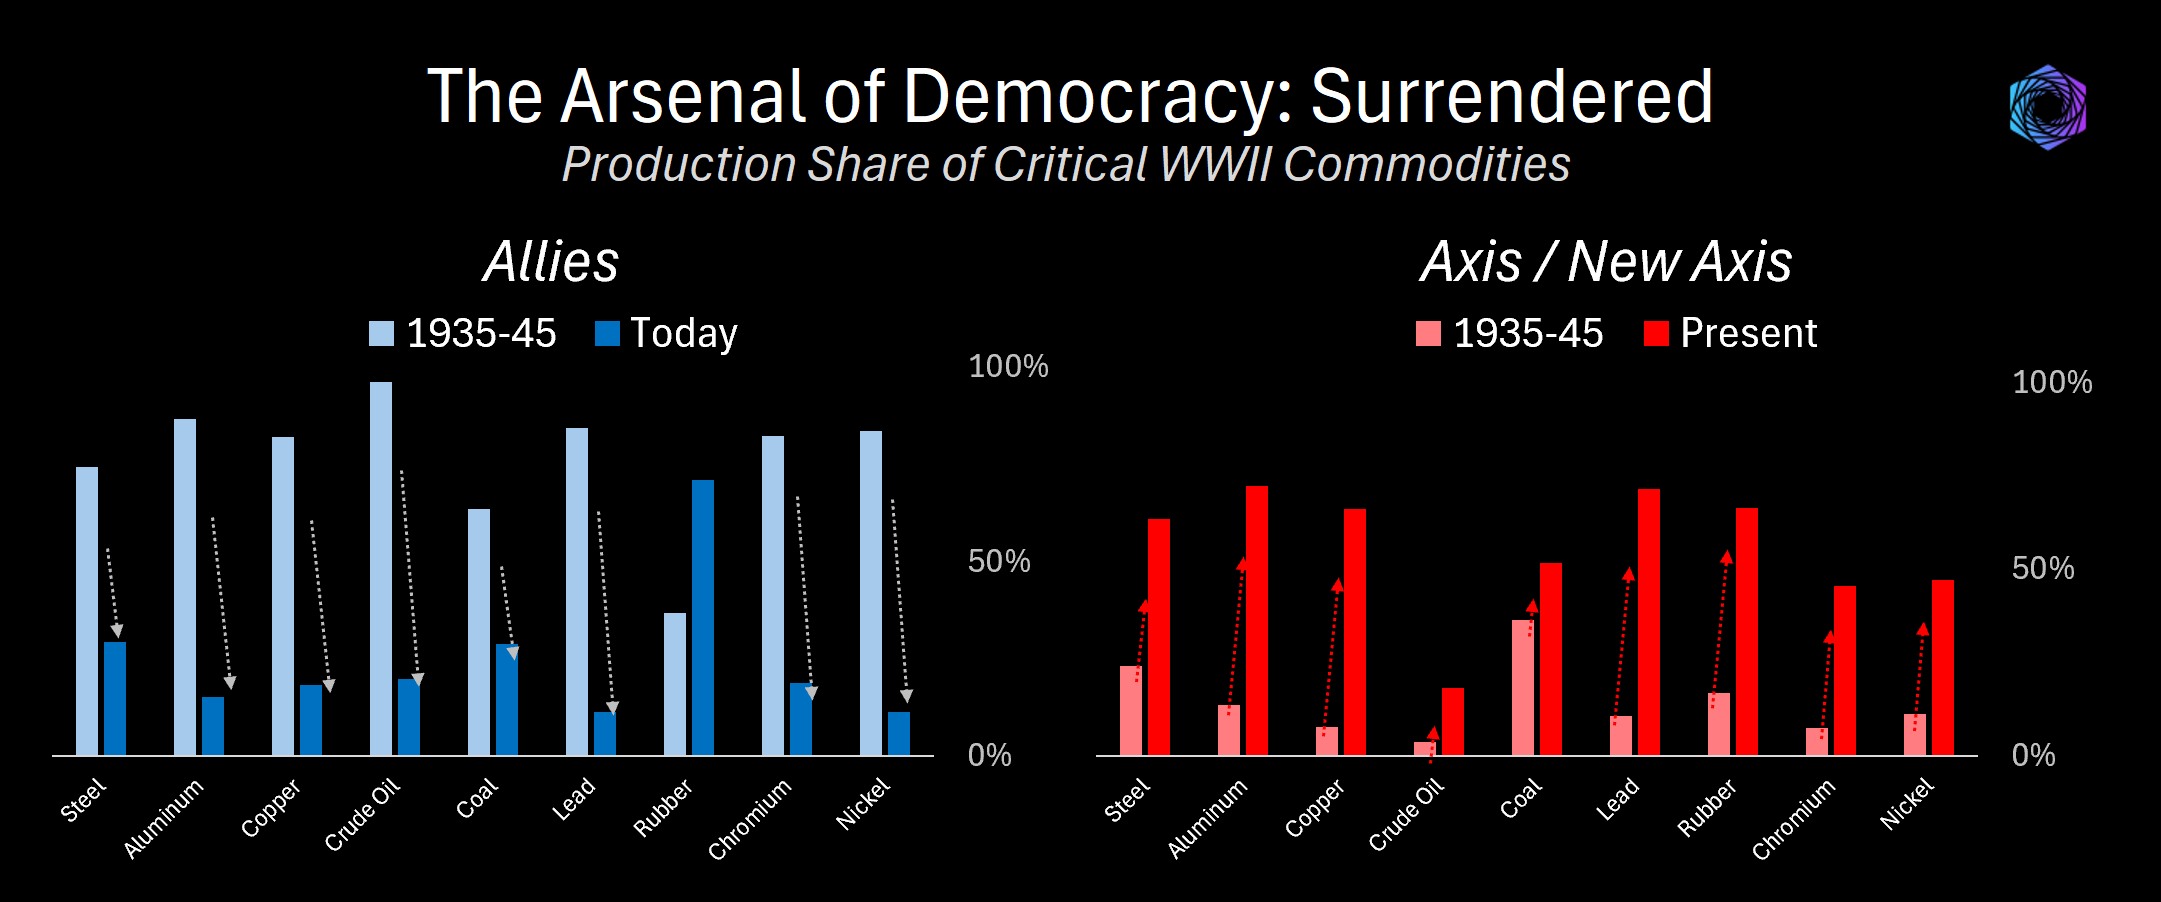
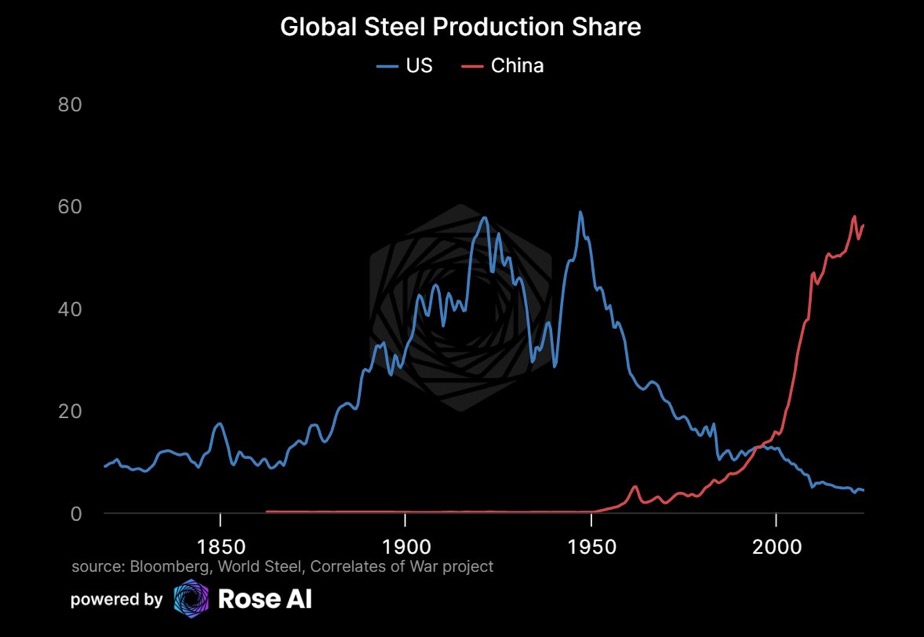
The US share of world steel today, down from nearly 60% in 1945. China makes more than half.
From “The Arsenal of Autocracy,” Campbell Ramble, Sep 2025 →What a Western buyer pays for yttrium oxide, against the price inside China.
When the gate closes, the world splits into two prices. Chinese manufacturers buy at home. Everyone else pays whatever material gets out. The gap is widest exactly where China holds the most.
Inside and outside
Two prices for the same metal.
Inside China, manufacturers buy at the domestic price. Outside, buyers pay for what gets through the gate. Red is the price inside China, blue the price outside. Until 2024 they moved together. Now they don't.
Today, US dollars per kilogram (log scale)
Antimony, 2006–2026, US dollars per tonne
Customs value per tonne: China exports vs US imports, 2010–2025
Today: public trade-press quotes of Fastmarkets, Argus, SMM, S&P, Benchmark and CREIA, Jun–Oct 2026. China domestic prices exclude 13% VAT. Samarium's outside price is China's export price; scandium has no public outside quote; graphite's outside quote is mid-2025. Antimony: USGS annual price, UN Comtrade unit values, Fastmarkets and 100ppi quotes. Customs: UN Comtrade HS6 value ÷ weight, which mixes grades. Read it for direction, not level. Full sources on the data page.
The fourteen
Every one of them is gated.
Each tile shows how shut China's export gate is today for supply bound to the US, and how much more a Western buyer pays than a Chinese one. The red bar is the gate. Click any tile for the history, the projections and the sources.
Gate scores are our judgment of each control on a 0–10 scale. The method, sources and full history are in the data.
What we're building
Everything from the mine to the strategic reserve.
The West has mines and it has demand. What it lacks is the layer in between. China runs that layer as one system: mine, refinery, merchant, customer. In the West the pieces are scattered and nobody connects them. We're building the connection.
- Mine
- Refiner
- Merchant
- Customer
- Mine
- ?
- Processor
- ?
- Customer
Source
Metal already in American and allied ground and scrap that nobody recovers today. Thirty-three operating western mines sit on ore carrying antimony that almost none of them recover.
Convert
Mines come online faster than refineries. We secure the conversion capacity that turns concentrate into usable metal.
Certify
Every lot traced from the ground up, so manufacturers can show where it came from when the 2027 sourcing rules arrive.
Reserve
Compliant inventory held ready, so supply doesn't stop when the gate closes. A strategic reserve, privately run.
Deliver
To the makers of magnets, chips, batteries and munitions, alongside the public programs now financing the chain.